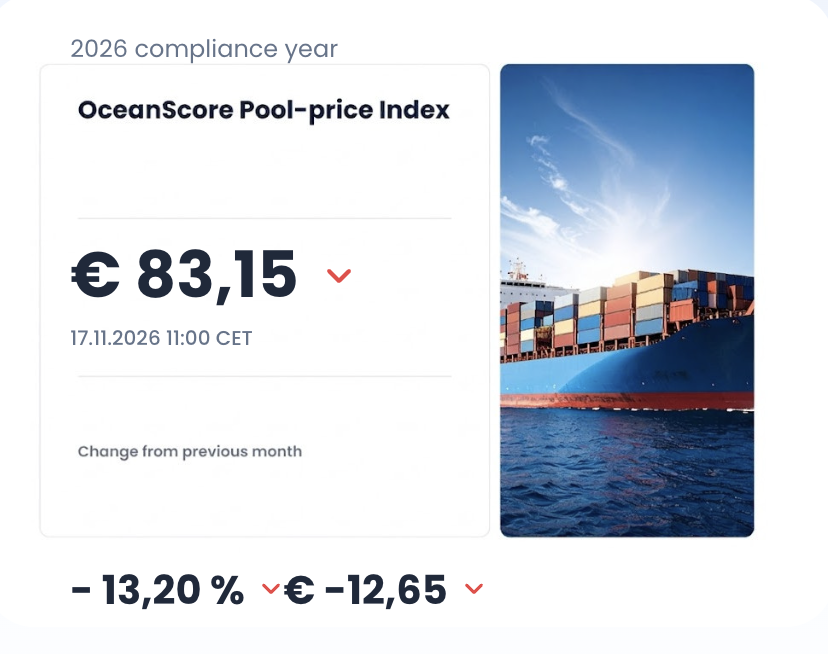
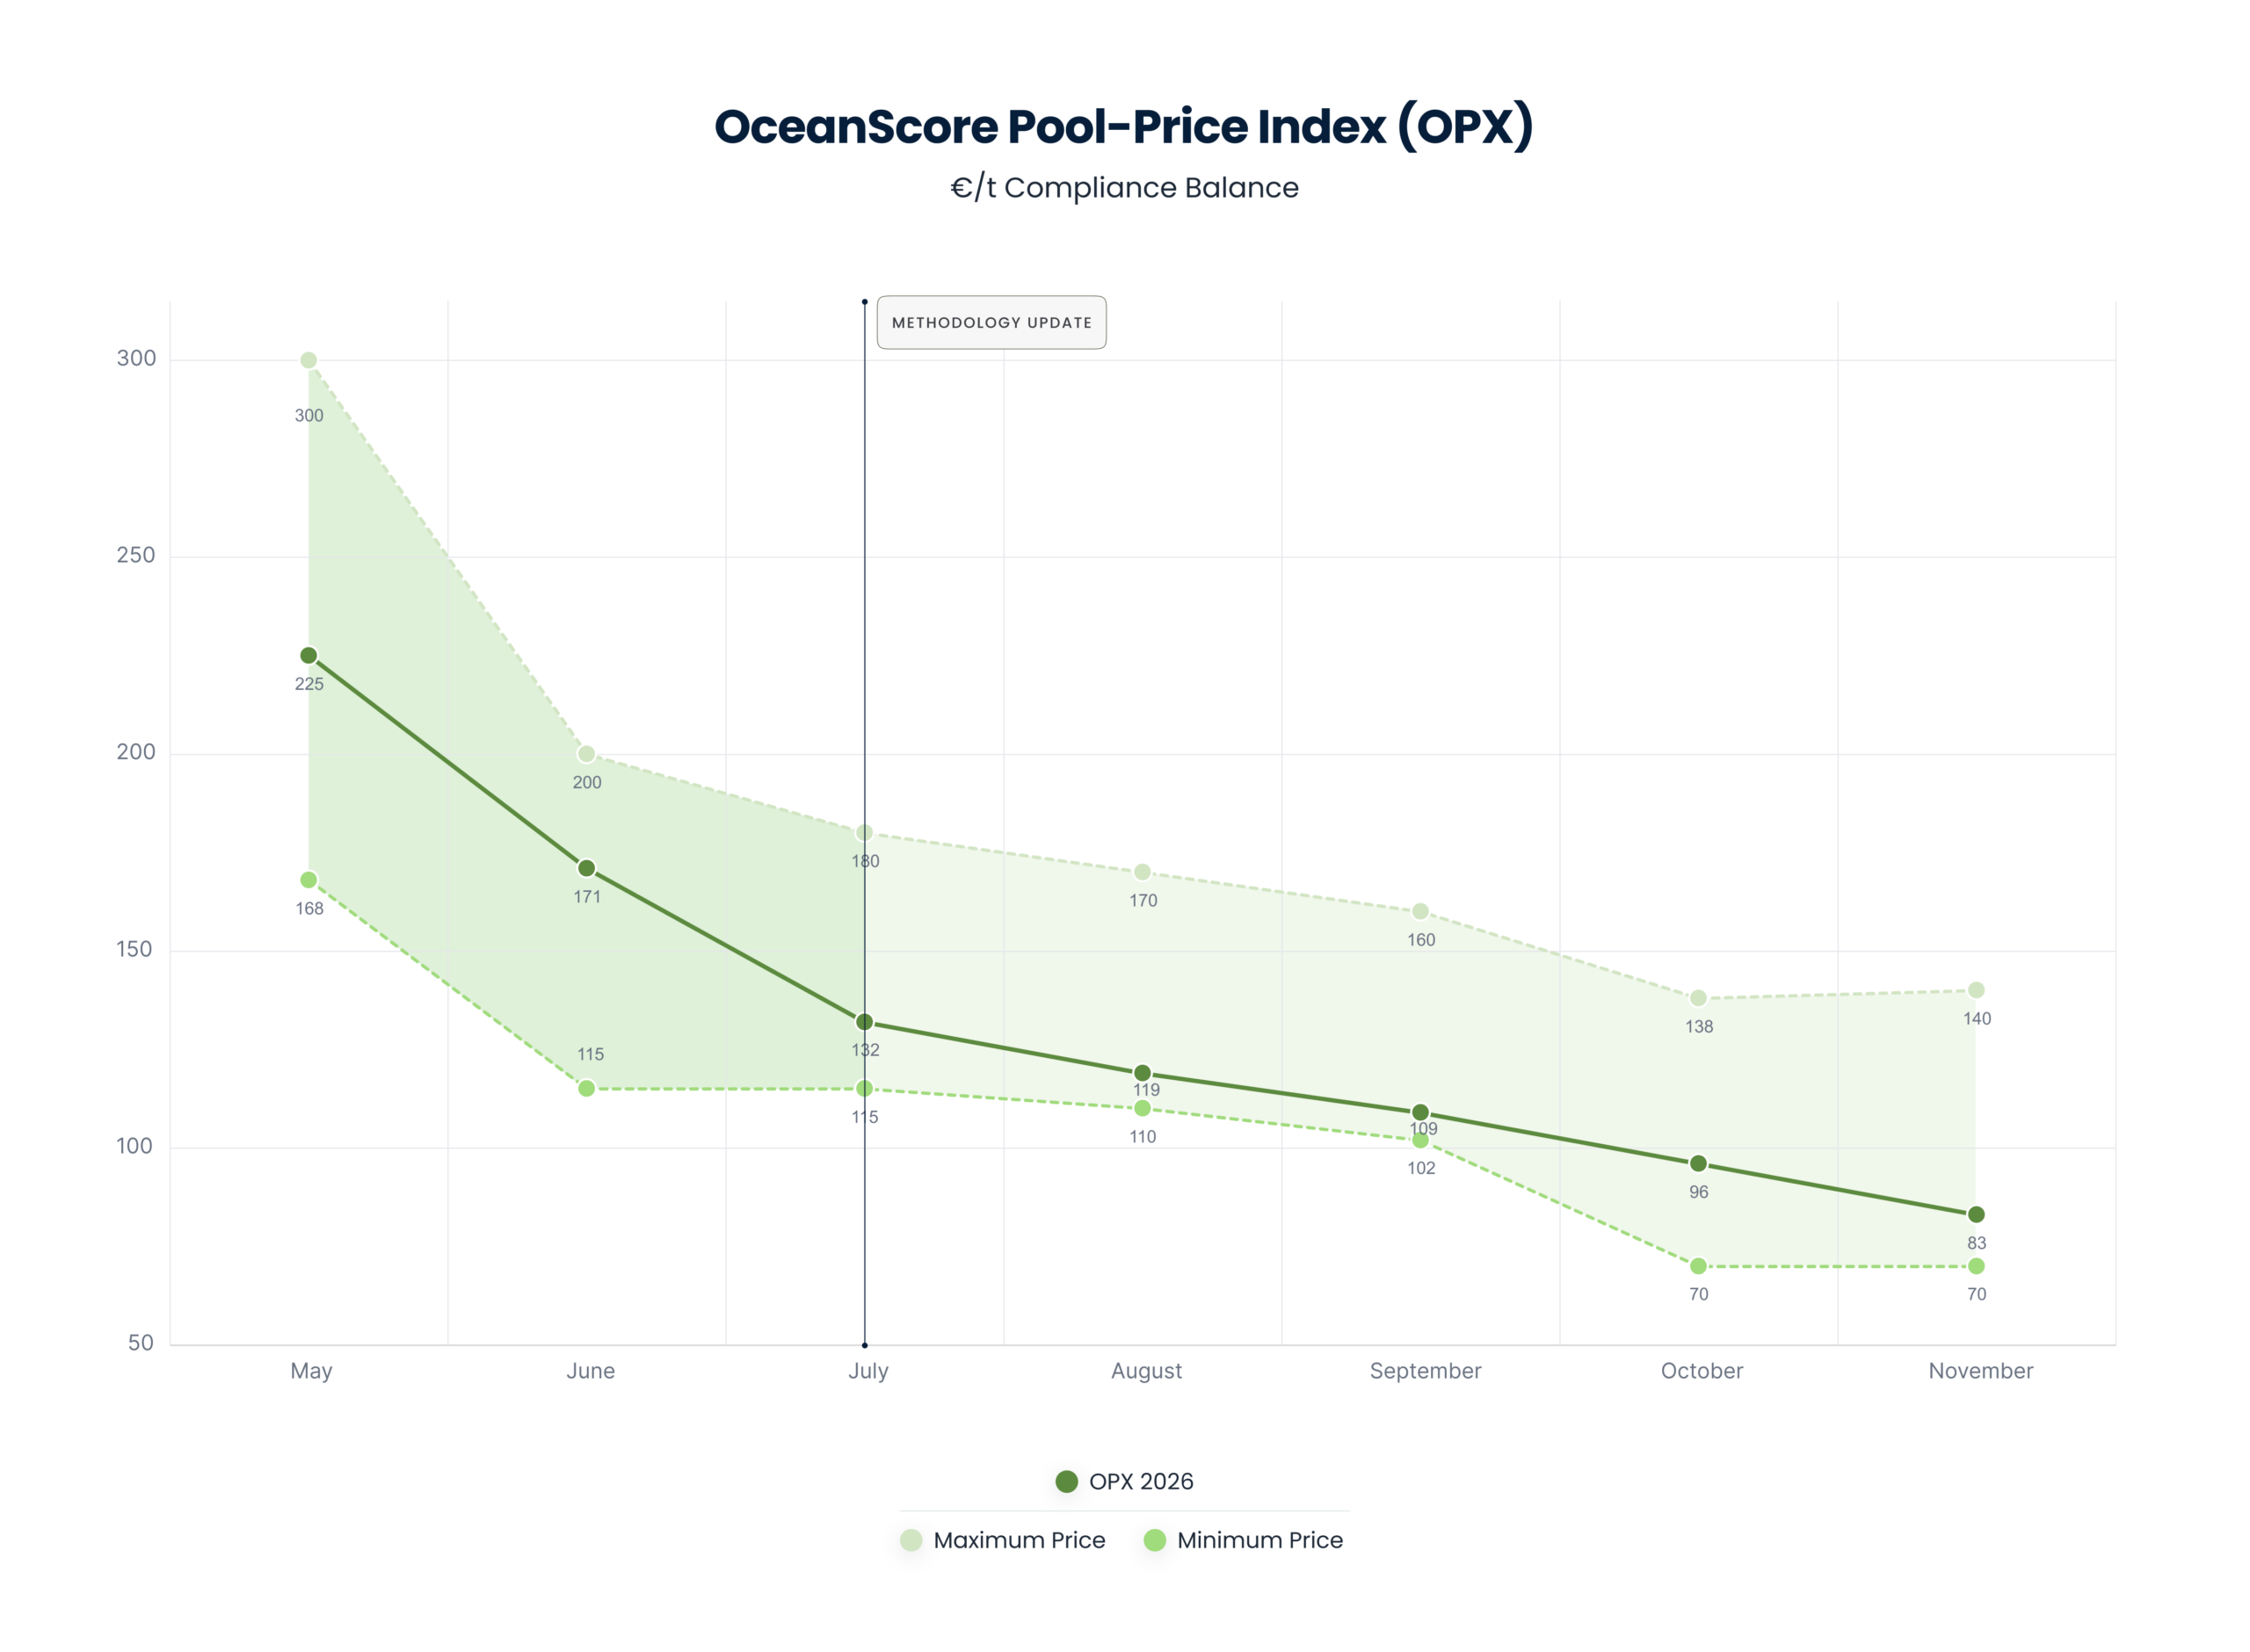
The OceanScore Pool-Price Index (OPX) stands at €83.15/tCO₂e in November, down from €95.80/tCO₂e in October, representing a decline of 13.2% month on month. November offer levels range from €70 to €140/tCO₂e, compared with €70 to €138/tCO₂e in October. While the lower end of the observed range remains unchanged, the continued decline in the index highlights sustained downward pressure on FuelEU surplus pricing.
Current surplus prices are becoming increasingly attractive for deficit holders, but they are also changing the economics of surplus generation. At these levels, prices are no longer sufficient to cover the costs of the full range of compliant fuels, raising questions about how sustainable current pricing will be and whether prices may begin to recover.
At the same time, the gap between pooling prices and FuelEU surcharges remains substantial. With surcharges in freight rates often reflecting penalty-based levels of approximately €640/tCO₂e, and pooling available at around €80/tCO₂e, the potential margin reaches approximately €560/tCO₂e. OceanScore estimates that the industry-wide opportunity arising from this difference has grown to around €1 billion.
This raises an important commercial question: how is this financial benefit shared between ship managers, owners and charterers? As pooling activity increases, understanding contractual arrangements and ensuring a fair distribution of compliance costs, efforts and rewards is becoming increasingly important.
Posted offers remain the primary reference for the OPX, providing a broad and continuously available view of FuelEU surplus pricing. As market conditions evolve, the index offers a transparent benchmark to support informed commercial decisions.
Click here to learn more about OceanScore’s FuelEU Pooling Marketplace.