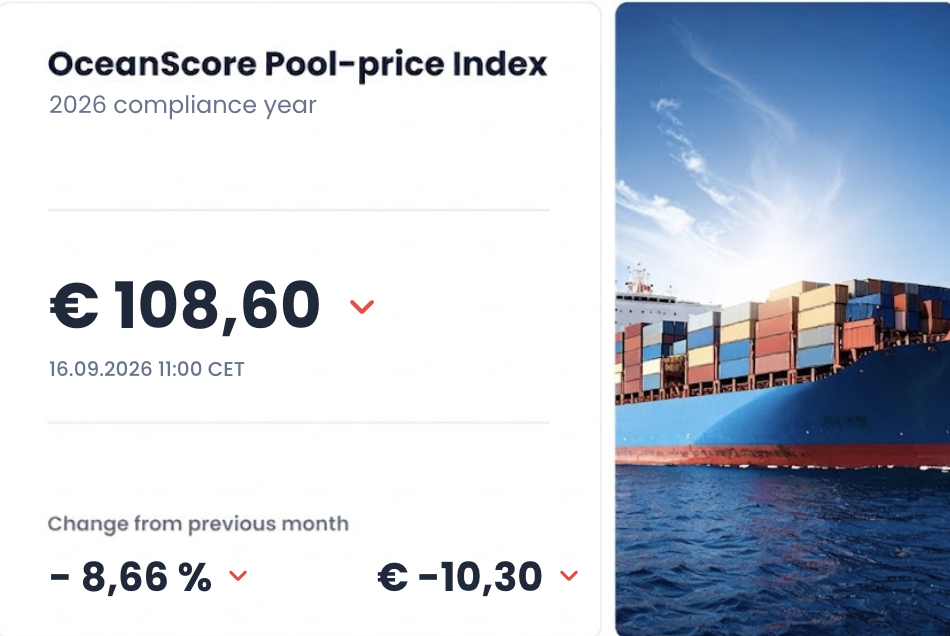
The OceanScore Pool-Price Index (OPX) stands at €108.60/tCO₂e in September, down from €118.90/tCO₂e in August. September offer levels range from €102 to €160/tCO₂e, compared with €110 to €170/tCO₂e in August. With both ends of the observed range moving lower, the latest figures point to continued downward pressure on FuelEU surplus pricing.
Following the quieter summer period – similar to last year – sellers return to the market, driving prices down to secure commercially relevant volumes.
The downward price pressures driven by surplus supply continuing to outstrip demand are compounded by currentlycomparatively low surplus generation costs, giving room for more aggressive pricing. Negotiations that drive final transaction prices up to 20% below offer ranges lead to prices below surplus generation costs, though, and are an indication of the market overshooting.
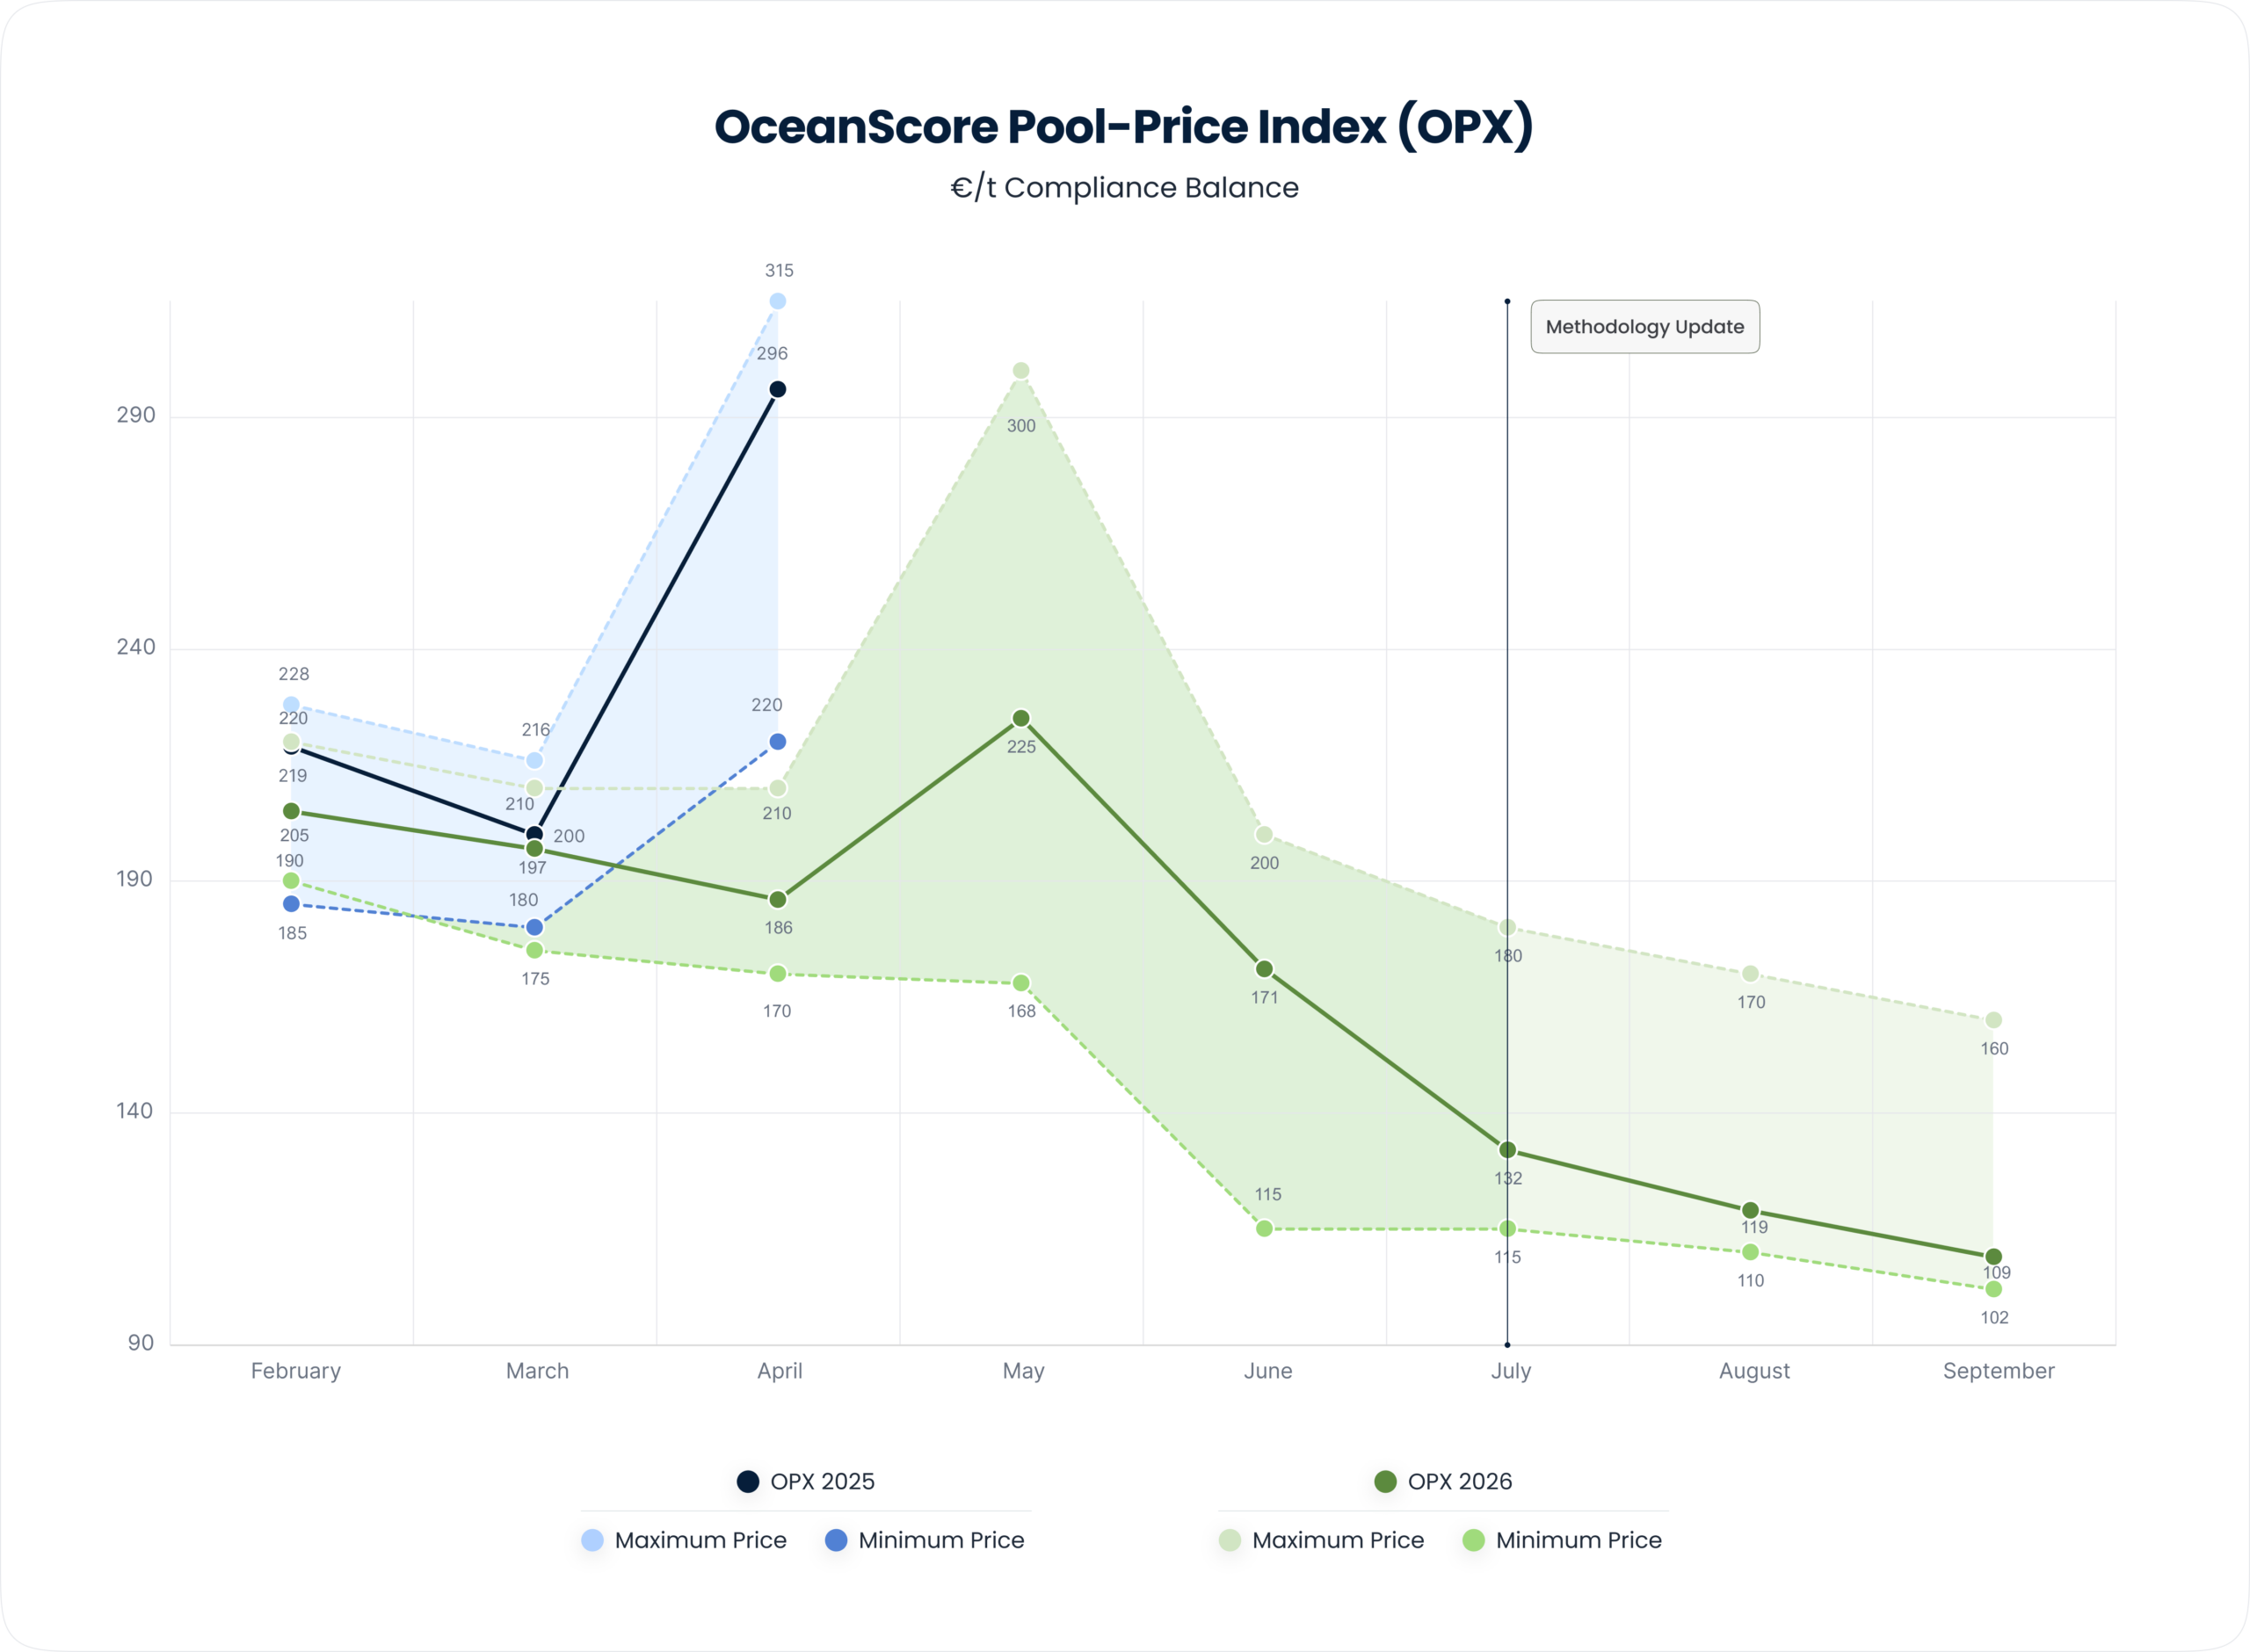
Together, these dynamics — the post-summer pickup in activity, a broadening seller base with more favorable cost structures, and intensifying competition for large-volume demand — are contributing to the compression in offer levels across both ends of the range.
Posted offers remain the strongest primary reference for capturing current market conditions. They provide a broader and more continuously available view of the market than completed deals and make the index less dependent on individual transactions or providers. The result is a transparent and reliable benchmark that provides ongoing visibility into FuelEU surplus pricing as the market continues to develop.
Click here to learn more about OceanScore’s FuelEU Pooling Marketplace.